What Is the Fastest Way to Sell My Parent's House if We Need Money for Assisted Living?
The fastest way to sell your parent's house is often a properly vetted cash offer that can close without a buyer's mortgage. But if you need money for assisted living right now, selling first may not be the only option. Depending on the home's equity, short-term bridge financing may help cover care while we handle the sale.
I'll tell you, this is one of those situations I run into quite a bit when I'm helping seniors and their families. Mom or Dad needs assisted living. Maybe they've had a fall, maybe they're dealing with memory issues, or maybe it's just gotten to the point where they can't safely live at home anymore. And now the family has a problem.
They've got a house that's worth a considerable amount of money, but most of that money is tied up in the property. Meanwhile, the assisted living community needs to get paid, and the family doesn't necessarily have the cash sitting in the bank. So the first thing somebody says is, "We need to sell this house as quickly as possible."
And I understand that. But here's where I want families to think about this a little differently. Is the real problem that we need to sell the house immediately? Or is the real problem that we need money immediately to get Mom or Dad into assisted living? Because those are two different problems. And depending on the situation, we may have several ways to solve them.
What Is the Fastest Way to Sell My Parent's House in Colorado?
If the goal is simply to sell the property as quickly as possible, a direct cash sale to a qualified investor may be one of the fastest options. Cash buyers don't need traditional mortgage approval, and some will purchase homes as-is. But the speed, price, contingencies, and actual closing date depend on the buyer and transaction.
Illustration: Reviewing a cash offer can be one way to explore a faster home sale, but the price and terms still matter.
So let's say Mom has a house in Broomfield, Arvada, Westminster, or somewhere in the Denver Metro area. The house has 40 years of belongings in it. The carpet is worn out, the kitchen hasn't been updated in decades, and there are probably some repairs that need to happen. Now the family is thinking they've got to clean everything out, fix the house up, put it on the market, find a buyer, and wait for closing.
Well, not necessarily. We may be able to sell the property directly to an investor who is willing to take it in its current condition. That could eliminate a considerable amount of preparation, and if the investor is purchasing with cash, we may avoid some of the delays associated with mortgage financing.
But here's the thing. Just because somebody says they're a cash buyer doesn't mean they're going to close tomorrow. We still need to verify they have the money, understand their contingencies, review the title, and make sure they can actually perform. And we also need to compare what they're offering with what the property might be worth through another selling strategy. Because the fastest offer isn't necessarily the best offer.
How Long Does It Normally Take to Sell a House in Broomfield or the Denver Metro Area?
Local market data shows that selling a home often takes weeks rather than days. In September 2026, Broomfield County had a median of 47 days on market, while REcolorado reported 33 median days in the MLS for sold Denver Metro listings. Neither figure includes every step of preparation and closing.
Now, those are important numbers because families sometimes assume they can put a sign in the yard on Monday and have the money in their bank account on Friday. Sometimes things move quickly. But that's not something I would ever want a family counting on without a plan.
According to Realtor.com's September 2026 Broomfield County housing report, the median sold price was $605,000, with homes selling at approximately 100% of their asking price on average.
And according to the September 2026 REcolorado Denver Metro Housing Report, the median closed price across the metro area was $575,000, with 2,898 completed sales during the month.
Those are market-wide statistics, and the two reports measure different groups of properties. They don't tell us exactly how long your parent's house will take to sell. And here's another thing. Days on market generally doesn't represent the entire time from the first walkthrough to money being available after closing.
We may still need to deal with contents, repairs, inspections, title work, and whatever financing the buyer is using. That's why I want to build a plan around the family's actual timeline instead of assuming everything will happen quickly.
Should We Sell the House As-Is to One Cash Buyer or Let Multiple Investors Compete?
Both approaches can work, but I prefer to explore whether we can create competition rather than simply accept the first investor offer. A direct sale may be straightforward and fast. Exposing the property to several qualified investors may produce stronger offers, although competition, pricing, and closing timelines are never guaranteed.
Here's something I've learned from years of working with investment properties. If you call one investor, you're going to get that investor's opinion of what the house is worth. And that investor is going to look at the property, figure out what they think they can make on it, and give you an offer that makes sense for their business.
There's nothing wrong with that. Investors need to make money too. But what if we put that same property in front of a whole bunch of qualified investors? Now we've potentially got multiple people looking at the opportunity, running their numbers, and deciding what they're willing to pay. That's a different situation.
Sometimes an investor sale is exactly the right answer, especially when the property needs substantial work or the family has a very tight timeline. But I still want to know whether we can do better than the first offer.
| Selling Strategy | Potential Advantage | What We Need to Consider |
|---|---|---|
| Direct Cash Investor | Potentially fast, often as-is | Offer amount, buyer qualifications, terms |
| Competitive Investor Bidding | Multiple investors can compete | Buyer demand, preparation, closing ability |
| Traditional MLS Listing | Broad exposure to buyers | Preparation, showings, financing, timing |
| Online Bidding Platform | Potentially creates buyer competition | Pricing, platform terms, buyer participation |
| Bridge Financing, Then Sell | May fund care before closing | Loan costs, equity, repayment risk |
These are general strategies, not guaranteed outcomes or closing timelines. The best approach depends on the property, financing, legal authority, and the family's needs.
Can You Really Sell a Difficult Property in Just a Few Days?
Yes, an unusually fast sale is sometimes possible when the circumstances, buyer, legal documentation, and title work all line up. I've personally worked through transactions involving very difficult property conditions and extremely short timelines. But those outcomes are exceptions, and I would never promise another family the same closing speed.
Let me tell you about a transaction we handled on Clarkson Street in Englewood. This was a difficult situation. The homeowner was terminally ill, didn't have family or friends available to help him, and wanted to sell his house quickly so he could direct the proceeds toward causes that were important to him. He was hoping to direct nearly $300,000 toward those causes. And time was absolutely critical.
A senior advisor contacted me, and I went out to meet with him in rehab that same day. Now, the house was one of the worst hoarding situations I've ever encountered. It was a mess. But we didn't have time to organize a major renovation or spend months preparing the property for a traditional listing. So we had to figure out another way.
I worked through the necessary documents, coordinated mobile notaries, helped secure his personal belongings, and connected him with an attorney to address his wishes for the estate. Then we marketed the property directly to more than 500 vetted investors.
According to our transaction records, we got that property from the initial call through closing and funding in approximately four days. That's an exceptionally fast transaction. And I'm not sharing that story to tell you I can sell every property in four days. I can't promise that.
I'm sharing it because sometimes the circumstances require a completely different approach from a traditional home sale. We have to understand the situation, figure out what's possible, and then execute.
What if My Parent's House Is Full of Belongings or Needs Major Repairs?
A house full of belongings or needing major repairs can still be sold. The family doesn't necessarily have to complete a full cleanout or renovation before finding a buyer. Depending on the property, we may use a professional cleanout, make limited repairs, or market it directly to qualified investors willing to take on the work.
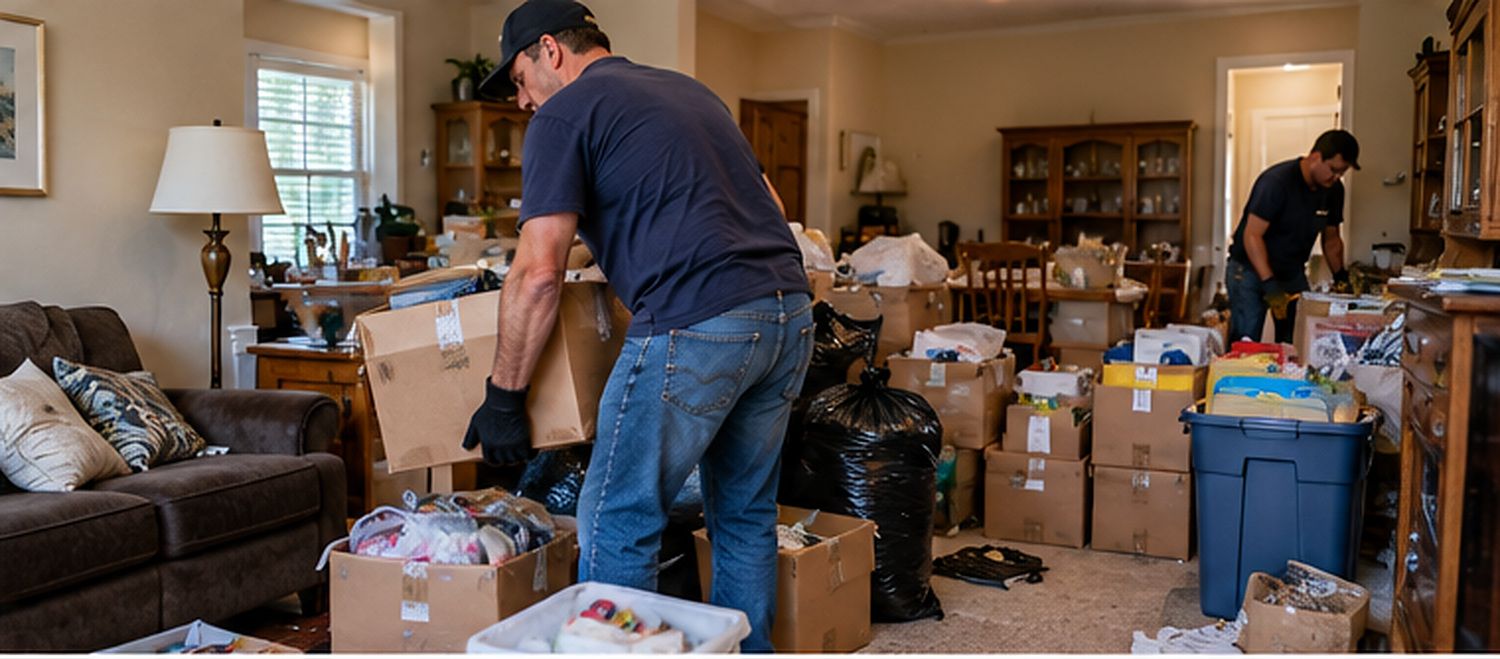
Illustration: Difficult-condition properties can require significant cleanout work. This image is not a photograph of the actual Ensenada Street property.
Here's another real example, and this one is especially relevant to assisted living. We had a senior transition on Ensenada Street in Aurora. The homeowner needed assisted living, and the property was in an extreme hoarding situation. I'm talking about a 2,200-square-foot duplex that ultimately required 11 roll-off dumpsters to clean out.
Eleven dumpsters. So this wasn't something where we could just have somebody come in, vacuum the floors, and put the house on the market. We had to coordinate crews to remove the contents, donate what could be donated, and dispose of the rest appropriately.
Once we got the property cleared, we could see the interior needed a full renovation. So now we had a decision to make. Do we spend the money and time renovating the entire property? Or do we approach investors who are already set up to handle that kind of project?
After evaluating the property, we decided to focus on investors. We marketed the duplex to our network of approximately 500 investors and held a one-day investor open house. We had approximately 40 to 50 investors come through.
That created competition for the property, and we got it under contract immediately after the investor-focused marketing. Our records show that the transaction closed within one week of going under contract.
Now, that's a complicated property that needed a tremendous amount of work. But we found a way to get it sold. And there's another important piece of this particular transaction. We also arranged financing to help the senior get the care she needed.
Can We Get Money for Assisted Living Before My Parent's House Sells?
Yes, in some situations, we may be able to arrange short-term financing secured by the home's equity. That can give the family money for assisted living, moving expenses, and property preparation before the sale closes. But bridge loans come with interest, possible fees, repayment obligations, and risks that need to be understood.
Illustration: Bridge financing may provide access to home equity before a sale closes, subject to loan approval, costs, and repayment terms.
This is one of the things that makes my senior real estate work a little different. A lot of families assume they have to sell the house first, get the money, and then move Mom or Dad into assisted living. But sometimes we can reverse that order. And I'll tell you why that's important.
According to the 2025 CareScout Cost of Care Survey, the median assisted living cost in Colorado is $6,584 per month for a private one-bedroom accommodation. That's approximately $79,005 a year. And two months at that monthly median would be $13,168, before additional entrance fees, moving costs, or special care expenses.
Now, that doesn't mean every facility charges those exact amounts. It gives you an idea of the financial commitment families may be facing.
So let's go back to our Ensenada Street transaction in Aurora. In addition to coordinating the property cleanout and sale, we arranged a $30,000 bridge loan through one of our private lending relationships. That funding helped cover the cleanout, limited repairs, and one month of assisted living.
Which meant we could address the senior's immediate care needs while still working through the property. That's a big deal.
Now, I want to make something very clear. A bridge loan isn't free money, and it isn't the right answer for everybody. The loan is typically secured by a lien against the property. We need to understand the interest rate, fees, repayment deadline, and what happens if the house takes longer than expected to sell.
The Consumer Financial Protection Bureau's guide to using home equity explains why borrowing against a house needs to be approached carefully. The borrower is responsible for repayment, and failure to meet the loan requirements can put the property at risk.
So we're going to run those numbers before making a decision. But in the right situation, bridge financing can give a family another option. Instead of rushing the sale because they need money this week, they may be able to get their parent moved and then deal with the house properly.
Should We Fix Up the House or Sell It Exactly as It Sits?
That depends on the property's condition, the cost of improvements, the available cash, and how urgently the family needs money. Sometimes an as-is sale makes the most sense. Other times, cleaning the property and making a few targeted improvements can produce a better financial result. We need to compare the actual numbers.
Illustration: Comparing an as-is offer against a prepared home sale can help families evaluate their potential net proceeds.
One of the things I don't like doing is walking into a house and giving the family just one recommendation. I've spent years evaluating properties, estimating renovation costs, and building spreadsheets to compare different investment and sale scenarios. I'm kind of a spreadsheet geek. So when I look at one of these senior properties, I want to see the different possibilities.
What if we sell it exactly as it sits? What if we clean it out and give it a little spit shine? Maybe we replace some carpet, paint the walls, clean up the landscaping, and make a few basic repairs. What if we go further and bring the house up to the standard of competing homes in the neighborhood? Or what if we do a full renovation?
Then I put the numbers together. How much will the improvements cost? How long might they take? What could the house realistically sell for? What are the holding expenses and selling costs? And most importantly, what does the family actually net?
Because here's the thing. If we spend an additional $60,000 on a house and only increase the sale price by $50,000, we haven't improved the family's situation. That's a hypothetical example, but it illustrates why the math matters.
And if Mom or Dad needs money for assisted living, every dollar matters. At the end of the day, I want to maximize what actually ends up in their bank account. Not just chase the highest possible sales price.
Can We Sell My Parent's House As-Is Without Making Repairs or Disclosing Problems?
You may be able to sell a home as-is without completing repairs, but that doesn't automatically eliminate legal disclosure requirements. In Colorado, sellers still need to address applicable disclosure obligations, and brokers have responsibilities concerning known adverse material facts. The contract, circumstances, and information actually known to the seller all matter.
This is another area where families sometimes get confused. They think that if we sell a house as-is to an investor, we don't have to worry about anything. Well, not exactly. As-is generally means the buyer is agreeing to purchase the property in its present condition, subject to the terms of the contract.
It doesn't automatically mean we can ignore known problems or required disclosures. The Colorado Real Estate Commission's 2026 Seller's Property Disclosure form explains how sellers report information to their current actual knowledge when completing the required form under the contract.
And sometimes we're dealing with an adult child who hasn't lived in that house for 20 years. They may have very limited knowledge about the roof, plumbing, electrical systems, or other property conditions. That's something we need to handle accurately.
My goal is to make sure we understand the property's condition, present the information appropriately, and work with buyers who know what they're purchasing. That helps us avoid creating another problem while we're trying to solve the first one.
What if We Have Power of Attorney, Probate, or Conservatorship Issues?
Legal authority can affect how quickly your parent's house can be sold. If you're signing under power of attorney, administering an estate, or working through conservatorship, we need to confirm that the appropriate person has authority to complete the transaction. Getting an attorney and title company involved early can help identify possible delays.
This is something I always want to look at before we get too far down the road. Because sometimes the house is ready to sell, we've got an interested buyer, and the biggest obstacle isn't the property. It's the paperwork.
Maybe Mom or Dad can no longer sign documents, and we need to review an existing power of attorney. Maybe there's a conservatorship issue. Or maybe a parent has passed away, and the family is trying to sell the house through an estate. Those are all situations I've encountered.
And I've learned that the earlier we get the right legal and title professionals involved, the better. Because there's no sense creating a fast marketing plan if we don't yet have someone who can legally sign the closing documents.
I don't provide legal advice, and I don't determine whether a particular document gives someone authority to sell. That's where we work with the appropriate Colorado attorney and title company. Then I can focus on the real estate side and coordinating what needs to happen.
What Should We Do First if Mom or Dad Needs Assisted Living and We Need Money Right Away?
Start by figuring out how much money is needed, when it's needed, and how much equity is in the property. Then evaluate the home's condition, legal authority, and potential selling strategies. Rather than immediately accepting an investor offer, compare how quickly each option could provide funds and what your parent would actually net.
Illustration: The priority is finding appropriate care for Mom or Dad while developing a realistic plan for the house and the finances.
Here's how I like to approach these situations.
- Figure out the care needs. Where is Mom or Dad moving? How soon? What's the entrance cost, monthly payment, and expected level of care?
- Look at the financial picture. How much cash is available? Is there a mortgage? How much equity might be in the house?
- Make sure we have legal authority. Who owns the property, and who can legally make decisions and sign documents?
- Evaluate the house. What's the condition? How much work does it need? What kind of contents and repairs are we dealing with?
- Build multiple selling scenarios. Compare a direct investor sale, competitive bidding, a traditional listing, and improvements where appropriate.
- Explore funding if necessary. If the immediate challenge is paying for assisted living, determine whether an appropriate financing option is available.
- Choose a plan and execute. Once the family understands the options and chooses a path, we coordinate what needs to happen to reach closing.
I also encourage families who need senior-care resources to contact the Denver Regional Council of Governments Area Agency on Aging, which serves Broomfield and surrounding counties. They can help families understand available aging services and support resources.
And here's the important thing. Every one of these situations is different. Sometimes the family needs an immediate cash sale. Sometimes a little property preparation makes sense. And sometimes we can solve the financing issue first so everybody has some breathing room.
The family is driving the bus. My job is to show them their options, put real numbers behind those options, and help get the work done.
Who Can Help Us Sell Our Parent's House Quickly for Assisted Living in the Denver Area?
If Mom or Dad needs assisted living and you're trying to figure out how quickly you can sell their house, I can help you evaluate the real estate options. We'll look at the property, determine what money is needed and when, compare selling strategies, and work toward the best practical outcome for your family.
I'm Scott Jensen with ReZion Realty, brokered by eXp Realty, in Broomfield, Colorado. I help seniors and their families throughout Broomfield, Arvada, Westminster, Thornton, and the greater Denver Metro area. And I'll tell you, a lot of the situations I work on are anything but normal real estate transactions.
Sometimes we're dealing with an urgent assisted living move. Sometimes it's a house full of belongings, a major renovation, a probate issue, or a family that simply doesn't have the money available to get things moving. That's the kind of work I do.
I don't want to just put a sign in the yard and hope somebody buys the house. I want to understand what's actually happening, figure out the options, and put together a plan that makes sense.
Sometimes selling quickly is absolutely the right answer. Other times, we may be able to find a way to fund the move first and take a little more time with the house. And at the end of the day, I want to make sure we're maximizing what Mom or Dad actually walks away with.
So if you're dealing with something like this, give me a call. Let's look at the property, figure out what kind of money you need and when you need it, and compare your options. We'll put together a plan and work toward the finish line.
Scott Jensen | ReZion Realty, brokered by eXp Realty
Phone: 720-352-7704
Email: scott@rezion.us
Important: This article is provided for educational purposes and is not individualized legal, tax, financial, or lending advice. Selling timelines, prices, financing eligibility, interest rates, and net proceeds vary by property and circumstances. Home-equity borrowing involves repayment obligations and the risk of losing the property if the borrower defaults. Consult appropriate lending, legal, tax, and senior-care professionals before making decisions. Past client transactions are examples and do not guarantee similar results.
Recent Posts